For a lot of business owners, the moment they realize their books need help isn’t a calm, planned decision. It’s an envelope from the IRS. Or an email from the bank saying the loan didn’t go through.
If that’s where you are right now, take a breath. These moments feel huge, but they’re very common and very fixable. And they’re often telling you something useful about your books.
If you got a tax notice
First: don’t panic, and don’t ignore it
Most IRS and state notices aren’t accusations. Many are generated automatically when something on your return doesn’t match information the agency received from someone else, like a 1099 from a client or a platform like PayPal or Stripe.
What does matter is the deadline. Here’s what to do right away:
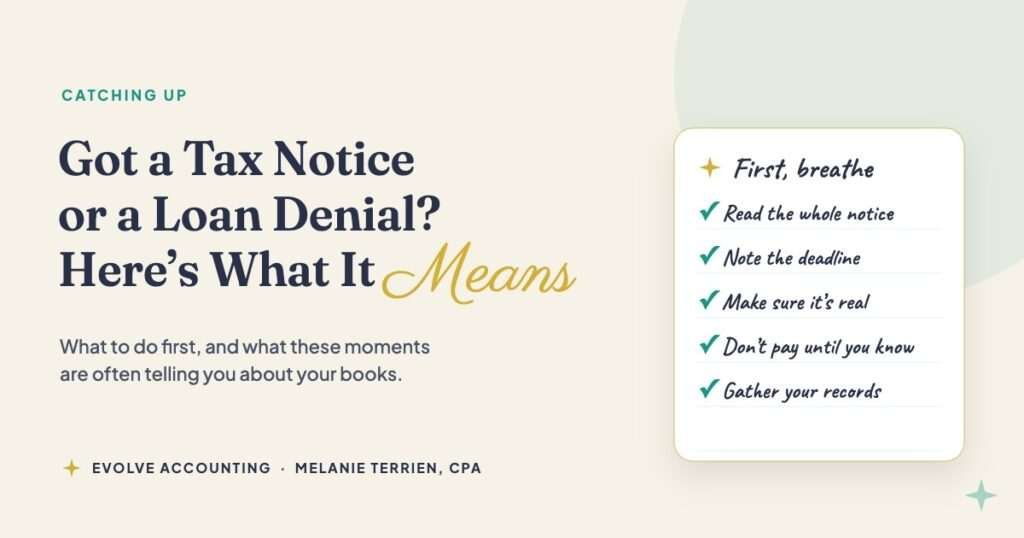
- Read the whole notice. Look for the notice number (usually in the top or bottom right corner) and the date you need to respond by.
- Make sure it’s real. The IRS typically contacts you by mail first. Be wary of calls, texts, or emails demanding immediate payment.
- Don’t pay or agree to anything until you understand it. Sometimes the notice is right. Sometimes it isn’t. You’re allowed to respond with documentation.
- Gather your records. Bank statements, 1099s, and your books for that year are what you’ll need to figure out what happened.
What it’s often telling you about your books
In my experience, notices usually trace back to a few common issues: income that wasn’t fully recorded, deposits that were counted twice (or not at all), or personal and business activity mixed together. Clean, reconciled books make it much easier to respond with confidence, and to keep it from happening again.
If your loan was denied
A loan denial stings, especially when your business is doing well. But lenders are usually looking at a few specific things, and financial records are often where applications get stuck:
- Current financial statements. Many lenders want an up-to-date Profit & Loss and Balance Sheet, not just last year’s tax return.
- Numbers that agree with each other. If your bank deposits, your books, and your tax return tell three different stories, that’s a red flag for an underwriter.
- Clear separation between business and personal money.
- Proof of cash flow that shows you can comfortably make the payments.
It’s completely reasonable to ask the lender what specifically held up your application. Their answer tells you exactly what to fix before you apply again.
The common thread
Whether it’s a notice or a denial, the underlying message is usually the same: your records haven’t kept up with your business. That’s not a character flaw. It happens to busy owners all the time.
The fix is getting your books accurate, reconciled, and current. From there, responding to a notice or reapplying for financing gets a lot less stressful. My Diagnostic Review is a good first step: I look at where things stand and give you a clear plan and quote.
If you’re holding one of these letters right now, book a free discovery call. Bring the notice or the lender’s email, and I’ll help you figure out what it means and what to do next. No judgment, I promise.